

SoFi: Bank, Investing & Crypto
by Social Finance, LLC
3.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.8
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
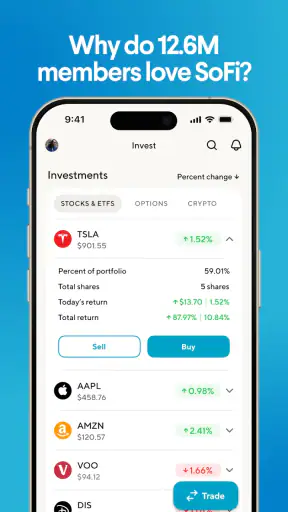
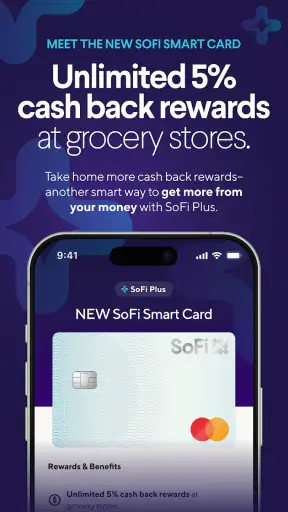
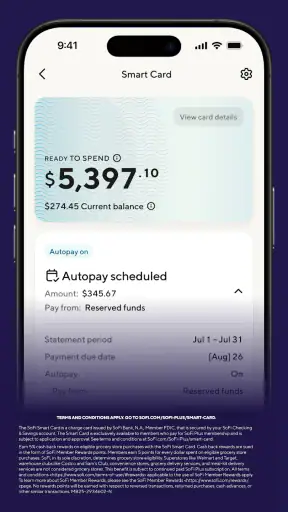
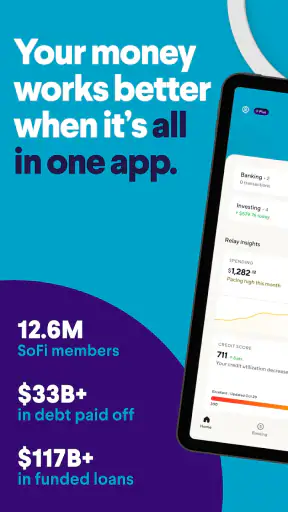
 Analysis by Getfullapps
SoFi is the kind of finance app that looks simple from the outside but becomes more interesting once you use it as a daily money hub. It brings checking and savings accounts, credit cards, investing, and crypto into one mobile experience, which can be convenient if you prefer fewer separate financial apps. I reviewed it with a practical question in mind: does putting these services together actually make everyday money management easier, or does the wider scope create more places to get stuck?
My short answer is that it can be a useful choice for someone who wants a broad view of their finances and is comfortable handling several types of financial activity in one account ecosystem. It is less convincing for a person who wants a highly specialized investing platform, a dedicated crypto exchange, or a banking app with almost no setup decisions. The convenience is real, but it comes with the responsibility of checking which part of the app you are using before you move money or make a financial decision.
Where the experience usually gets stuck
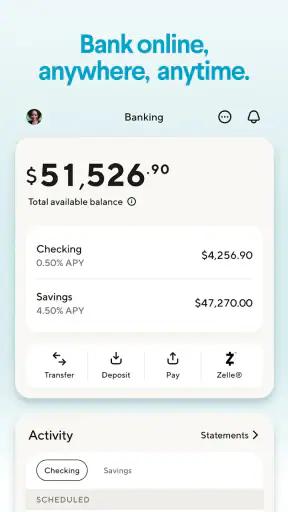
The first source of friction is that SoFi is not just a checking app. The same product covers everyday banking, saving, credit, investing, and crypto. That breadth is its main appeal, but it also means the home experience can feel busier than a traditional bank app. A new user may open it expecting one clear balance and instead need to understand which account, product, or activity they are viewing.
I found that the safest habit is to slow down whenever an action involves moving money. Before confirming anything, I would check the source account, the destination, and whether the action belongs to banking, investing, or crypto. Those areas may sit close together in the same app, but they serve very different purposes. A transfer between everyday accounts is not the same decision as buying an investment, and neither should be treated like a routine card payment.
Another common sticking point is expecting every financial task to behave like a normal banking transaction. Investing and crypto introduce different timing, risk, and confirmation expectations. If a user sees a balance that does not change immediately or expects an action to settle like a card purchase, frustration can follow even when the app is working normally. The most important adjustment is to separate “the app accepted my request” from “the financial result is already complete.”
SoFi also asks users to make more choices than a basic checking account does. You may need to decide whether money belongs in spending, saving, investing, or another part of your financial plan. That flexibility is valuable, but it means the app cannot make the right decision for you. I would not recommend opening several products at once simply because they are available together. Starting with the service you actually need makes the interface easier to understand and makes later troubleshooting much simpler.
The product is free to download and use as an app, and it is published by Social Finance, LLC. Its broad audience is reflected in an Everyone content rating, but that should not be confused with financial simplicity. The app may be suitable for a wide range of adults, while the decisions made inside it still deserve careful attention.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What to check before blaming the app
When a balance, transfer, or account screen looks wrong, I would first confirm that I am signed into the intended profile and looking at the intended product. This sounds obvious, but a combined finance app makes it easier to confuse an account balance with an investment value or to look at a summary screen instead of the detailed activity attached to it.
Next, I would review the activity history rather than relying only on the large number shown at the top of the screen. A summary can be useful for a quick glance, while the transaction list gives better clues about whether money is pending, completed, reversed, or simply not part of the account being viewed. Reading the individual entry is often more useful than repeatedly refreshing the main page.
I would also check the basics that affect every financial app: a stable internet connection, the current app version, and whether the phone is running a supported operating system. SoFi’s current version is 3.105.0, and the app supports Android 8.0 or later. If the app behaves strangely on an older phone, updating the operating system or installing the latest available app build is a sensible first step before attempting more disruptive fixes.
There is a practical reason to avoid immediately deleting and reinstalling a finance app. Reinstallation can remove locally stored preferences and may force you through additional sign-in or security checks. I would only take that step after confirming that login details and access to required verification methods are available. For a banking application, recovery access matters more than the small convenience of starting from a clean install.
Notifications deserve a quick check too. If you are waiting for an alert, the absence of a notification does not necessarily mean the underlying transaction failed. Phone-level notification settings, battery restrictions, or a muted notification category can prevent an alert from appearing. The activity screen inside the account is the better place to verify what actually happened.
A safer setup for everyday use
My preferred setup is deliberately narrow. I would begin by learning the checking and savings areas, confirming how balances and activity are displayed, and only then explore credit, investing, or crypto. This creates a clear reference point. If something later looks unfamiliar, I know whether it is a banking issue or a separate product area rather than trying to understand everything at once.
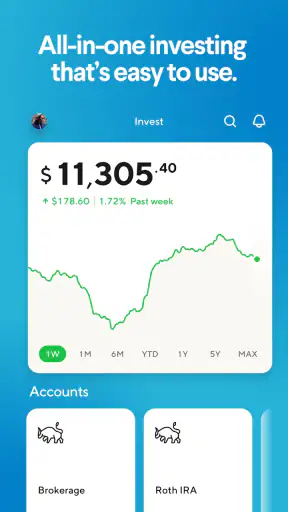
For a realistic example, imagine receiving income near the end of the week and using SoFi to divide it between spending money, savings, and an investment account. I would first verify that the incoming amount appears in the correct place. Then I would review each planned movement separately instead of treating the entire sequence as one operation. Afterward, I would check the activity records for all parts of the workflow. This takes a little longer, but it reduces the chance of overlooking a pending action or sending money to the wrong destination.
A useful, less obvious tip is to keep a plain-language note of your own intended money flow. For example: “income arrives here, regular spending stays here, long-term money goes there.” The note is not a feature of the app; it is a simple way to prevent the combined interface from turning your financial plan into a series of impulsive taps. It is especially helpful when banking and investing options appear within the same product.
Credit card users should apply the same discipline. A credit balance is not the same as available cash, and a card activity screen should not be read as though it were a checking account ledger. I would review payments and purchases in their own context, then check the checking or savings balance separately. Keeping those mental categories distinct is more useful than trying to make one total number represent everything.
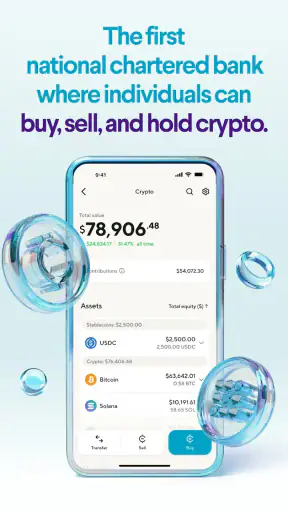
The same caution applies to crypto. Having crypto access alongside banking and investing may be convenient for users who already understand the risks, but it can also make speculative activity feel too close to routine spending. I would treat that section as a separate decision space, not as another savings pocket. Someone who wants only predictable banking may be better off ignoring that area entirely or choosing a simpler banking product.
Recovering when a workflow breaks
When an action appears stuck, my first response would be to stop repeating it. Tapping the same transfer or purchase button several times can create confusion about whether multiple requests were submitted. Instead, I would record what I intended to do, inspect the relevant activity list, and look for a pending or completed entry before trying again.
If the app closes, freezes, or returns to an unexpected screen, I would restart it and repeat the check from the account activity rather than assuming the last screen tells the whole story. A temporary display problem can make a completed action look unfinished, while a failed request can look similar until the transaction record is examined. The distinction matters because retrying a financial action is not as harmless as retrying a search.
For login trouble, I would use the normal account-recovery route and avoid creating a second account simply to get back into the app. A duplicate profile can make the situation harder to understand, especially when several financial products are involved. I would also be cautious about entering credentials after following an unexpected message or link. Opening the app directly is the safer way to verify an account issue.
If a transfer or payment is not visible, I would gather the basic details before contacting support: the account area involved, the approximate time, the amount, and whether the activity appears as pending, completed, or absent. This gives the support conversation a clear starting point. It also helps distinguish a display problem from a transaction that was never submitted.
One practical trade-off is that a single app can simplify support because several products are under one brand, but it can also make the question more complicated. “My money is missing” is not enough information when the money could relate to checking, savings, a card, an investment position, or crypto. Naming the exact product and activity type will usually produce a more useful troubleshooting path.
When the app is not the cause
Finance apps often get blamed for delays that originate elsewhere. A bank transfer may involve processing steps outside the phone, a card payment may depend on the merchant, and an investment or crypto action may not behave like an instant cash transaction. If the app records the request clearly, the next question should be what stage the transaction is in rather than whether the interface is broken.
Device conditions can also create misleading symptoms. A weak connection may load the dashboard but fail when a more sensitive action is attempted. An outdated operating system can cause instability even when other apps seem fine. Storage pressure, aggressive battery saving, or restricted background activity may interfere with normal loading and notifications. These are not SoFi-specific defects, but they are worth checking before making account changes.
There is also a human cause: choosing the wrong product for the job. If you want a stable place for routine spending, crypto may be the wrong destination even if it is available in the same app. If you want advanced investment research and specialized trading tools, a dedicated brokerage may fit better. If you only need a straightforward checking account, the extra sections may add more decisions than value.
Compared with using separate traditional bank, brokerage, and crypto apps, SoFi’s advantage is the reduced need to switch between services. That can make it easier to see a broader personal-finance picture and can reduce the number of apps competing for attention. The compromise is specialization: a unified app may not feel as focused as the best standalone tool for each individual task.
Its user base is substantial, with over five million installs, an average rating of 3.8 from around fifty-three thousand ratings, and around twenty-one thousand written reviews. Those figures suggest a widely used product with mixed experiences rather than a universally effortless one. I would read that as a reason to judge the app against your own needs, not as a guarantee that every device, account type, or workflow will feel identical.
My practical verdict
After using SoFi as a broad finance app, I see its strongest use case in the person who wants banking, saving, credit, investing, and crypto access organized under one roof. It is particularly appealing if switching between several specialized apps is the main problem you are trying to solve. The combined view can make your financial life feel more connected, provided you remain deliberate about which product you are using.
I would recommend starting slowly: learn the banking screens, inspect activity instead of relying only on summaries, verify every money movement before confirming it, and keep investing or crypto decisions separate from routine spending habits. Those steps address the most realistic sources of confusion without assuming that every delay is a software failure.
I would skip it if you want a minimalist bank with one clear purpose, if you need highly specialized investing tools, or if seeing speculative products beside everyday money would encourage decisions you would rather avoid. In those cases, separate services may provide better boundaries even though they require more apps.
The app was released on April 10, 2017, and its continued development is reflected in the current version. That history, together with its broad product range, makes it feel more like a full financial platform than a single-purpose wallet. Still, the platform approach only works when the user understands the differences between its sections.
Overall, SoFi is a capable choice for organized users who value convenience and are willing to verify details before acting. I would recommend it to a friend who wants a central place for several financial needs, with one warning: do not let the clean convenience of one app make different financial decisions feel identical. Use the banking tools for banking, treat credit carefully, and approach investing and crypto with their own level of attention. That mindset turns the app’s breadth from a source of friction into its most useful advantage.
Pros
- User-friendly interface for easy navigation.
- Comprehensive financial insights integrated.
- Offers a wide range of investment options.
- No commission fees on trades.
- Customizable alerts for account monitoring.
Cons
- Limited customer support options available.
- Some features require premium membership.
- Occasional app lag during peak times.
- Limited crypto offerings compared to others.
- No support for joint accounts.
FAQs for SoFi: Bank, Investing & Crypto
What features does the SoFi app offer?
The SoFi app provides a comprehensive suite of financial tools, including banking services, investment options, and cryptocurrency trading. Users can manage their spending, set savings goals, and access personalized financial advice. Additionally, the app offers loan refinancing, credit score monitoring, and educational resources to help users make informed financial decisions.
Is the SoFi app secure for managing my finances?
Yes, SoFi prioritizes user security with features like two-factor authentication, encryption, and continuous monitoring for suspicious activity. The app also complies with industry standards to protect user data. Users can rest assured that their financial information is safeguarded, allowing them to manage their finances with peace of mind.
How does SoFi's investment feature work?
SoFi offers a user-friendly investment platform with options for both active and automated investing. Users can trade stocks, ETFs, and cryptocurrencies, or opt for automated portfolios managed by SoFi's robo-advisors. The platform has no commission fees, making it accessible for beginners and experienced investors alike.
Are there any fees associated with using the SoFi app?
SoFi is known for its fee-friendly approach. There are no account fees, overdraft fees, or minimum balance requirements for their banking services. However, users should be aware of potential fees related to third-party services, especially when trading cryptocurrencies. It's advisable to review the fee schedule within the app.
Can I access customer support if I have issues with the SoFi app?
Yes, SoFi provides robust customer support through various channels. Users can access support via phone, email, or live chat directly within the app. Additionally, the SoFi website offers a comprehensive FAQ section and community forums where users can find answers to common questions and share experiences.

SoFi: Bank, Investing & Crypto
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mobilesupport@sofi.com, visit https://www.sofi.com, or review their https://www.sofi.com/online-privacy-policy.










